

Category: Real Estate
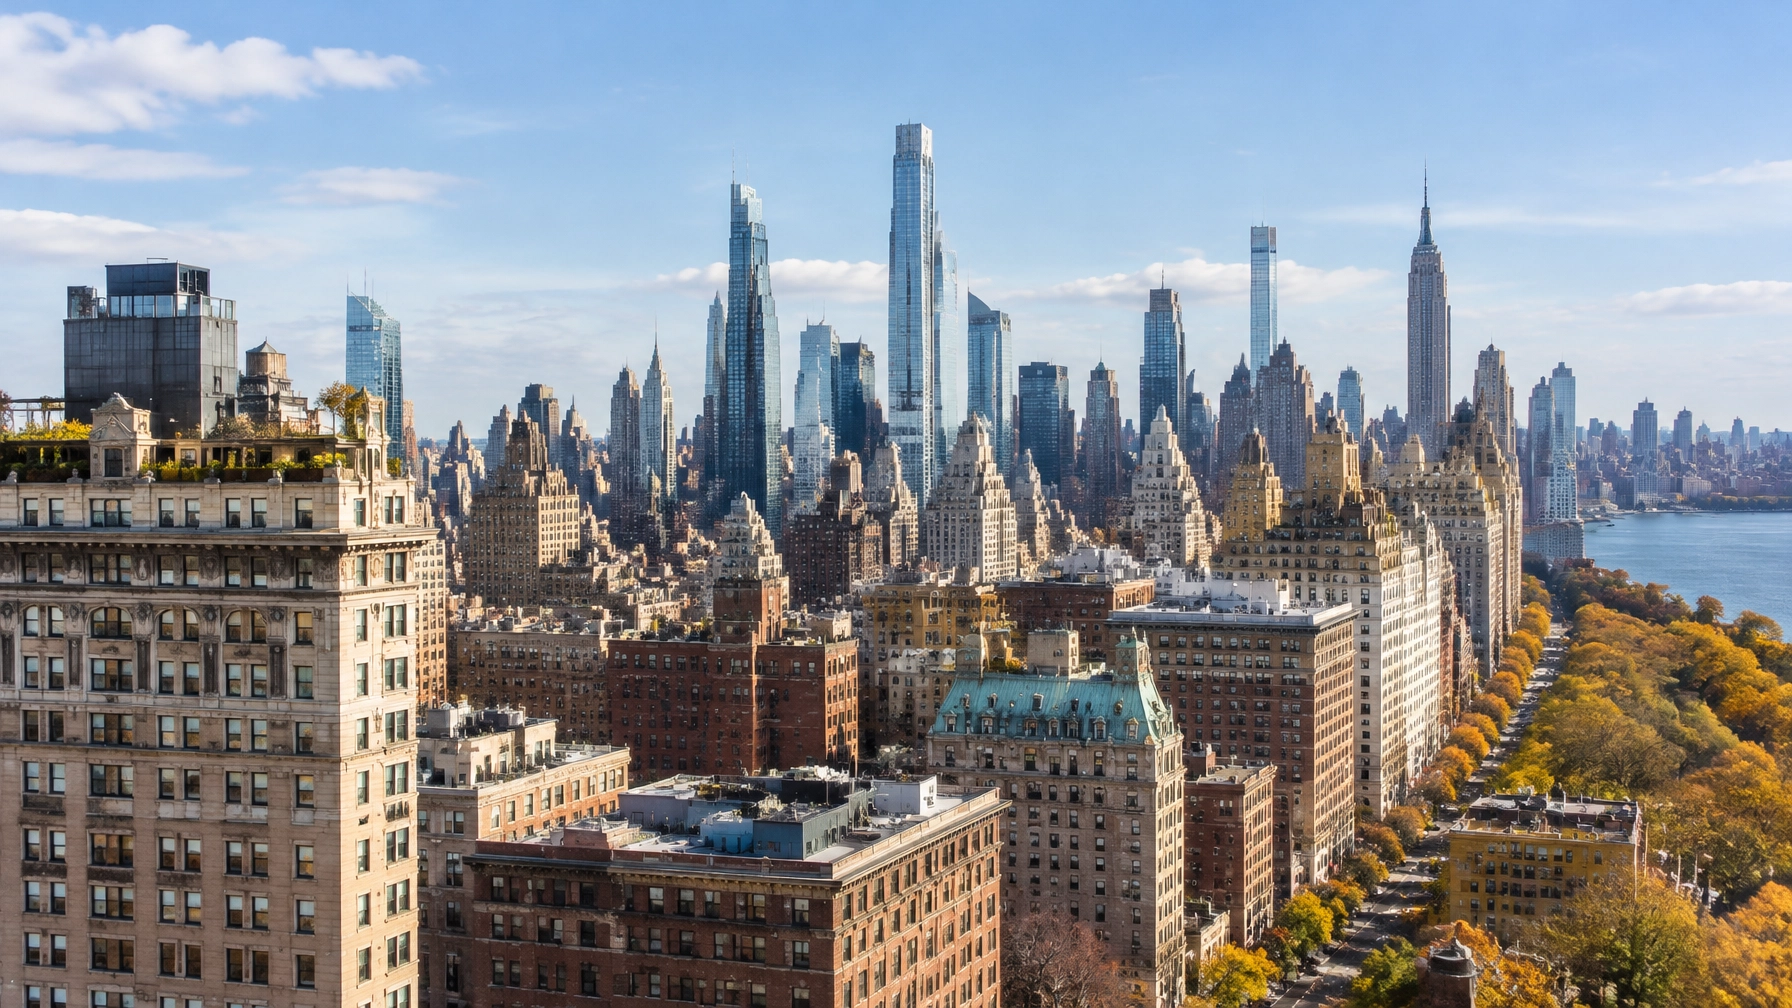
Manhattan’s third-quarter housing market paired a record median sale price with a jump in completed transactions, even as fewer buyers signed contracts and new-development options grew scarcer.
Closings rose 9% year over year to 3,625, while the median sale price reached $1.25 million, a record for a third quarter. But signed contracts fell 6% from a year earlier, a reminder that completed sales reflect deals already in motion while contract activity offers a more immediate view of buyer demand.
That split defines the latest NYC real estate trends: established demand and limited inventory are supporting prices, but high borrowing costs and added expenses are making some prospective buyers more cautious. For people tracking New York real estate news, the quarter offers a market that remains active, though not equally accessible across price points.
Prices and closings rose as contracts slowed
Manhattan recorded about $7.28 billion in residential sales volume during the quarter, up 10% year over year. Average price per square foot also increased, rising 2% to $1,751. The figures point to continued strength in closed sales, especially for properties that matched buyers’ preferences and budgets.
The decline in signed contracts complicates that picture. The 2,532 contracts signed in the quarter marked a 6% annual decrease and the slowest third-quarter pace since 2023. This does not mean sales abruptly stopped: closings and contract signings measure different stages of a transaction. A home closing in July or September may have gone under contract months earlier.
Instead, the gap suggests that the market’s current price strength is meeting a more restrained pool of new buyers. Limited selection may also be keeping would-be purchasers on the sidelines. When buyers cannot find a suitable home, they may delay rather than bid on a less suitable option.
A weekly rebound in early October offered a brighter near-term signal. Manhattan and Brooklyn both posted their strongest contract activity since early August, with Manhattan reaching 195 signed contracts and Brooklyn recording 122 in the latest weekly tally. That uptick shows that demand can move quickly when buyers see homes worth pursuing, but one strong week does not erase the quarter’s year-over-year decline.

Scarce new development is intensifying competition
New-development supply has tightened sharply. Sponsor-listed inventory fell 22% year over year to 564 units, putting it at a nearly 14-year low. With fewer newly built homes available, buyers seeking modern layouts, building amenities or new construction have a narrower set of choices.
Inventory totals can vary depending on how a market report defines and counts new development. A broader measure of Manhattan’s new-condominium pipeline also shows a constrained market, while indicating additional projects may come to market later in the year. The key point for buyers is that a low number of currently available sponsor listings does not mean development has stopped; it means that the flow of completed, actively marketed homes is limited relative to demand.
Tight supply can intensify competition for well-priced properties and make desirable homes harder to replace if a deal falls through. It can also strengthen sellers’ negotiating position, particularly when a property is move-in ready and priced in line with recent sales. Still, the market-wide price record does not guarantee that every listing will attract multiple offers: location, condition, monthly carrying costs and pricing remain decisive.
Buyers face a tougher affordability calculation
Mortgage rates add pressure to an already expensive purchase. Rates were at 7.57% in the latest market snapshot, raising monthly payments and narrowing the price range many financed buyers can comfortably consider. Manhattan’s $1.25 million quarterly median is a borough figure, not a measure of what a particular buyer can afford.
The cost calculation has also changed for some purchasers considering a second home. New York City’s non-primary-residence property surcharge, often discussed as a pied-à-terre tax, applies to certain qualifying homes that are not the owner’s primary residence. It is an annual surcharge, not a one-time fee paid only at closing. Eligibility and rates depend on factors including property type and value. Buyers should review the city’s surcharge rules and exemptions carefully and seek tax advice before making a purchase decision.
For buyers, the combination of higher financing costs, a limited choice of new homes and possible annual surcharges makes due diligence especially important. Comparing monthly payments, common charges, taxes and expected maintenance can provide a more useful picture than focusing on the asking price alone. Some purchasers may also broaden their search by considering different neighborhoods, older buildings or homes that need renovation, while weighing the additional costs and time those options can involve.
Sellers have leverage, but pricing still matters
For sellers, rising closings and a record third-quarter median are favorable signs. Fewer available new homes may help established properties stand out, and the October pickup in contracts suggests active buyers remain in the market.
But sellers should not mistake low inventory for unlimited demand. The decline in quarterly contract signings points to buyers who are more selective, and elevated mortgage rates can limit the number able to compete. A property priced well above comparable sales may sit even in a supply-constrained market. Accurate pricing, thoughtful presentation and clear information about taxes and building costs can help sellers reach qualified buyers.
The citywide snapshot also puts Manhattan’s price level in context. Across New York City, the median sale price was around $923,000 in the latest reported 30-day period, well below Manhattan’s quarterly median. These figures cover different time windows and should not be treated as a direct borough-to-city comparison, but they show how strongly neighborhood and borough shape the price of entry.
Brooklyn’s separate market has also drawn attention, with its median sale price recently reported at a record $1.2 million amid fewer deals. Readers can see related coverage in New York News Daily’s report on Brooklyn’s sales market.
Developers and investors weigh supply against costs
For developers, scarce new-development listings create an opening, but not a simple one. Limited competition from available new units can make a well-positioned project more visible. At the same time, a high-rate environment and cautious contract activity raise the stakes for choosing a price, product mix and launch schedule that can attract buyers.
The market’s thin inventory is not automatically a signal to build without restraint. Developers must account for construction and financing costs, the timing of delivery and the possibility that additional projects will enter the pipeline. Buyers, meanwhile, may weigh a new home’s amenities against its price and the availability of existing residences.
Investors face a similar balance. Rising median prices and low supply can support the value of well-located property, but they do not guarantee future appreciation or rental income. Financing expenses, operating costs, taxes and the surcharge on qualifying non-primary residences can materially affect returns. Investors considering a second home should distinguish expected resale value from cash flow and evaluate the applicable rules before committing.
What to watch next
Manhattan enters the final quarter of 2026 with an unusual combination: record pricing, stronger completed sales, fewer new-development listings and a slower year-over-year pace of signed contracts. The early-October rebound suggests buyers are still willing to act when the right property appears, but the next several weeks will show whether that burst becomes a sustained improvement.
For buyers, the central challenge is balancing timing with affordability. For sellers, the opportunity lies in reaching motivated purchasers with realistic pricing. Developers and investors will need to measure supply against financing, tax and construction costs.
The market remains active, but scarcity alone does not settle the question of value. In a high-cost environment, the strongest decisions will depend on the details of each home and the buyer’s full cost calculation, not Manhattan’s record median alone.